Best Money Apps of 2026: How to Automate Your Finances and Save More
Your smartphone has quietly become the most powerful financial tool you own. In 2026, money apps handle everything from splitting a lunch tab to investing spare change and negotiating your bills while you sleep. The right combination of apps can save you hundreds of dollars a year and hours of tedious admin. This guide breaks down how to choose, combine, and safely use these tools to put your finances on autopilot.
Having tested dozens of these platforms across budgeting, saving, and investing, I have learned that the winning strategy is not downloading everything. It is building a small, well-chosen stack that works together. Let’s explore how.
Why Money Apps Matter More Than Ever in 2026
Cash use continues to fall, and digital-first banking is now the norm rather than the exception. Money apps thrive in this environment because they remove friction. Instead of manually logging expenses or remembering due dates, you let software handle the repetitive work.
Automation also fixes the biggest weakness in personal finance: human forgetfulness. When savings transfers, bill payments, and investment contributions happen automatically, your progress no longer depends on willpower or a good memory. That reliability is why financial coaches increasingly recommend a solid app stack to beginners and pros alike.
The Main Categories of Money Apps
Before choosing tools, understand the categories. Each solves a different problem, and most people benefit from combining two or three.
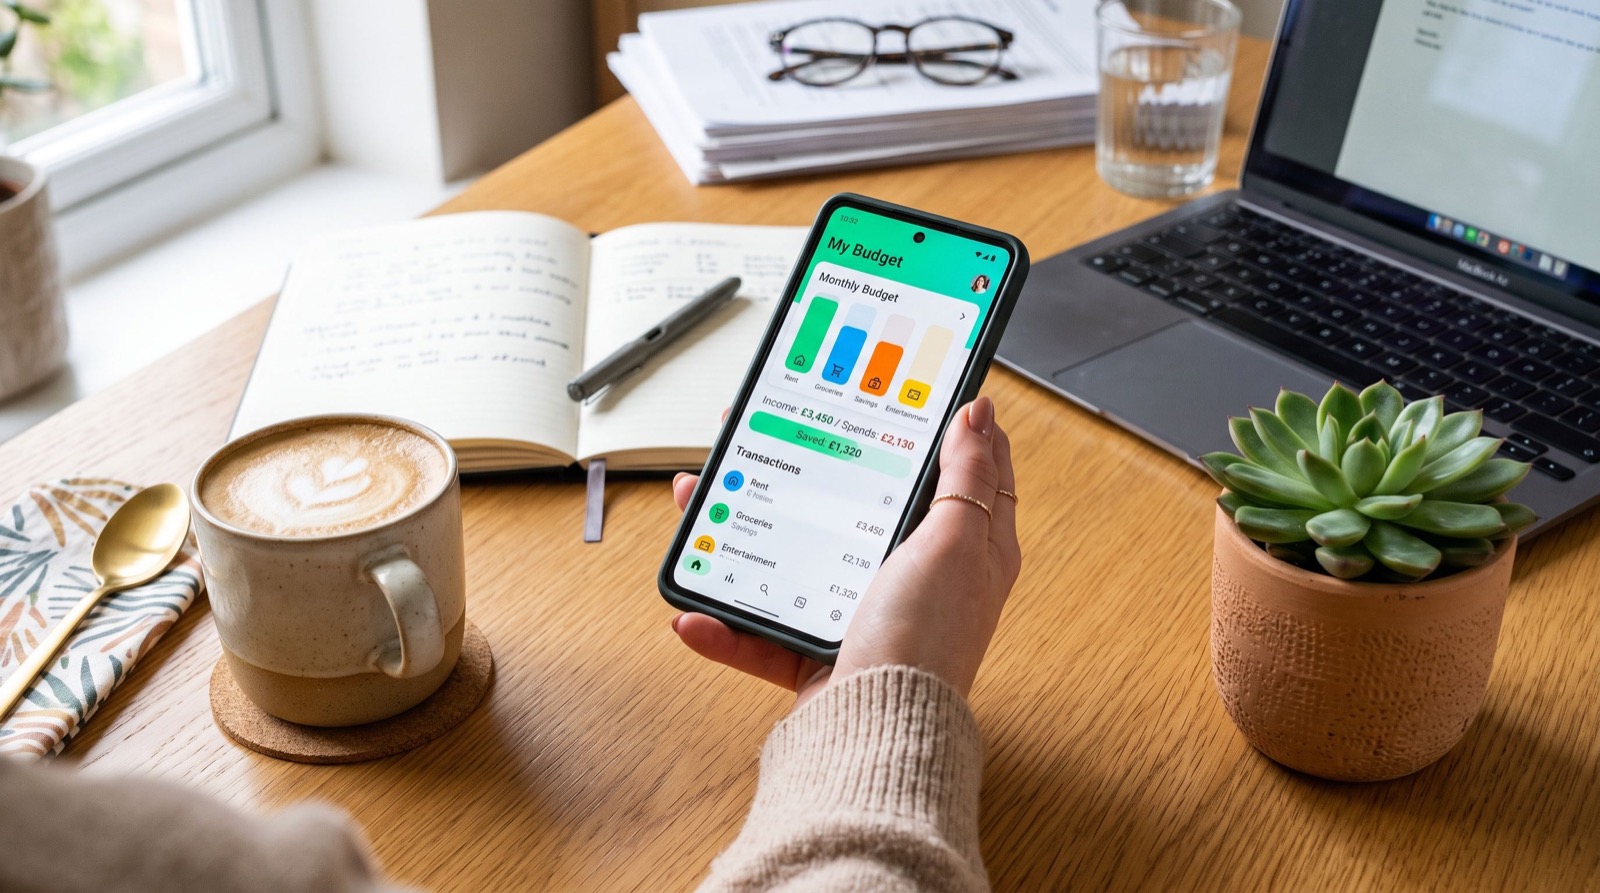
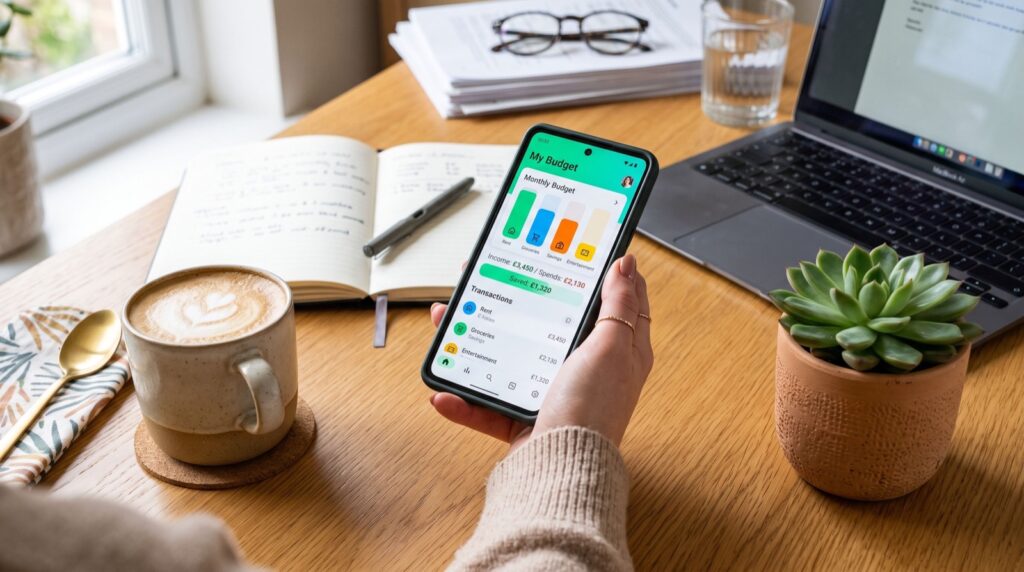
- Budgeting apps track spending and show where your money goes.
- Savings apps automate transfers and round up purchases.
- Peer-to-peer payment apps let you send and receive cash instantly.
- Investing apps open the market with fractional shares and low fees.
- Bill negotiation apps hunt for savings on recurring subscriptions.
For detailed reviews and setup walkthroughs, these curated money apps recommendations from WalletWisp help you match a tool to your specific goals rather than chasing hype.
How to Choose the Best Money Apps for You
The perfect app for your neighbor might be wrong for you. Focus on your biggest pain point first. If overspending is the issue, start with a budgeting app. If you never seem to save, an automated savings app matters most.
Evaluate each candidate against a short checklist:
- Does it sync securely with your bank?
- Are the fees transparent and reasonable?
- Is the interface simple enough that you will actually use it?
- Does it offer strong security like encryption and two-factor authentication?
Rounding up your research with a shortlist of the best money apps saves you from downloading and abandoning a dozen half-useful tools.
Which Money App Should I Download First?
Start with a budgeting app if you want visibility, or a savings app if you want automatic progress. Master one tool for a month before adding another. Layering apps too quickly leads to notification fatigue and abandonment.
Comparing Popular Money App Types
This table summarizes what each app type does best and the typical cost you can expect in 2026.
| App Type | Solves | Typical Cost | Automation Level |
|---|---|---|---|
| Budgeting | Overspending | Free–$15/mo | Medium |
| Savings round-up | Low savings rate | Free–$5/mo | High |
| Peer payment | Slow transfers | Free (fees on instant) | Medium |
| Investing | Getting started | Free–0.25% AUM | High |
| Bill negotiation | Overpriced subscriptions | % of savings | High |
Staying Safe While Using Money Apps
Convenience should never come at the cost of security. Digital fraud remains a real threat, so protect yourself with strong habits. The Consumer Financial Protection Bureau recommends enabling every available security feature and treating peer-payment transfers like cash, because sending money to the wrong person is often irreversible.
Follow these safety rules:
- Enable two-factor authentication on every financial app.
- Use a unique, strong password for each service.
- Avoid transferring money over public Wi-Fi.
- Only send money to people and businesses you trust.
- Review transactions weekly to catch errors fast.
Building Your Ideal Money App Stack
The smartest users combine a few complementary apps. A common winning stack pairs one budgeting app, one automated savings app, and one investing app. Together they cover awareness, safety, and growth without overwhelming you.
If you are setting up a new home or a home office and want your finances organized before the boxes arrive, planning ahead pays off. Coordinating a smooth transition with dependable specialists keeps moving costs predictable, which makes your budgeting app’s job far easier.
Common Mistakes to Avoid With Money Apps
Even great tools can backfire when used carelessly. Watch out for these frequent slip-ups that quietly cost users money and momentum in 2026.
- Downloading too many apps: A cluttered phone leads to ignored notifications and abandoned tools. Keep your stack lean.
- Ignoring instant-transfer fees: Many peer-payment apps charge a percentage for immediate transfers. Wait for the free standard option when timing allows.
- Leaving large balances in a payment app: These balances often lack full deposit insurance. Sweep extra cash into an insured, high-yield account.
- Skipping the free trial evaluation: Test premium features before paying. Many users pay for tiers they never fully use.
- Turning off alerts: Transaction alerts are your first line of defense against fraud. Keep them on.
Avoiding these mistakes is often more valuable than finding the perfect app. A disciplined approach with a few solid tools consistently beats a phone crammed with unused financial software. Review your app stack every few months and remove anything you no longer open.
How Money Apps Support Bigger Financial Goals
Beyond daily convenience, money apps quietly advance long-term goals. Automated round-ups build a house deposit over years. Recurring investment transfers grow retirement savings while you barely notice. Budgeting insights reveal spending leaks that, once plugged, free up cash for the things you truly value. When you connect small daily tools to a clear long-term vision, the compounding effect becomes genuinely powerful over time.
Frequently Asked Questions
Are money apps safe to link to my bank account?
Reputable money apps use bank-level encryption and read-only connections that cannot move your money without permission. Stick to well-reviewed apps, enable two-factor authentication, and monitor your accounts regularly.
How many money apps should I use?
Two or three well-chosen apps usually cover most needs: one for budgeting, one for saving, and one for investing. Adding too many creates clutter and notification fatigue that leads to abandonment.
Do money apps cost money?
Many offer strong free versions, while premium tiers unlock advanced features. Investing apps may charge a small management fee, and bill negotiation apps typically take a percentage of what they save you.
What are the best money apps for beginners?
Beginners do well with a simple budgeting app plus an automatic savings app. These build awareness and momentum quickly without requiring financial expertise or a large starting balance.
Final Thoughts
The best money apps of 2026 turn good financial intentions into automatic action. By choosing a focused stack, prioritizing security, and letting automation handle the busywork, you free up time and mental energy while your savings and investments grow quietly in the background. Pick one app today, master it, and build from there. Your finances will feel calmer within a single month, and the compounding benefits only grow from there.